
 7 minutes ago
4
PROTECT YOURSELF with Orgo-Life® QUANTUM TECHNOLOGY
Orgo-Life the new way to the future Advertising by AdpathwayKUALA LUMPUR, Malaysia, November 10 (IPS) - Trump and Netanyahu went all out for regime change in Tehran. This month, their electorates gave them regime changes, albeit not quite what they wanted. The wars continue, but the politics have changed.
Trump’s military spending
In Trump’s second term, the US president and the outgoing Republican-controlled Congress have shown even less respect for the Constitution.
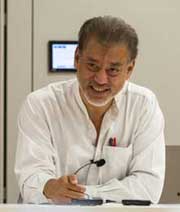 Jomo Kwame Sundaram
With his new chief of staff, Trump may not even seek approval for additional war spending from Congress, which alone has the authority to tax and spend under the US Constitution.
Trump wanted a $1.5 trillion military budget for fiscal 2027, starting in October, up from $860 billion in Biden’s last budget, an increase of over $600 billion, or nearly 2.0% of GDP!
Financing the massive increase in US military spending would require substantial tax increases. Without them, Trump would have to increase the budget deficit, risking even higher interest rates.
Greater military spending and higher interest rates have diverted economic and human resources from more socially useful purposes. Besides exhausting the economy, it is also economically and socially wasteful.
War raises interest rates
Before Trump and Netanyahu attacked Iran on 28 February, the interest rate on 10-year US Treasury bonds was around 4.0%. It subsequently rose to around 4.7% by late August.
Higher interest rates make borrowing more expensive for individuals and governments. Having to pay more, corporate borrowers will surely pass the costs on.
Higher expected inflation alone cannot explain the higher interest rates. Unexpectedly, after more than six months of war, expectations of future inflation were slightly lower than in February!
Higher interest rates probably reflect broader changes in expectations, as investors now expect much larger US budget deficits than early this year.
The US Federal Reserve now projects that the Fed funds rate, widely seen as reflecting investor attitudes, will be higher in 2027 and 2028 than before the war.
Likewise, long-term interest rates on other countries’ debt have risen, indicating Trump’s war has raised interest rates worldwide.
Raising interest rates ineffective
Raising interest rates does little to address inflation caused by deliberate supply-side disruptions. Trump appointed Kevin Warsh as Fed Chair to bring down interest rates, but the Chairman has not obliged so far.
Inflation has been above the Fed’s 2.0% target for over half a decade. With US unemployment rising in 2024, it lowered interest rates. After Trump’s re-election, inflation rose due to stockpiling in anticipation of his tariffs, and then the tariffs themselves.
Inflation would probably have declined again if not for the second attack on Iran, which pushed oil and other prices up. Relief from inflation now hinges on the very uncertain prospects of ending the war.
As higher inflation has been the pretext for the Fed to raise interest rates, it should lower rates if prices fell. Likewise, when the AI bubble bursts, interest rates would likely decline too.
Macroeconomist Dean Baker suggests that the Fed has kept interest rates up to appear to be doing something. With wage growth barely over 3.0% and falling, income has been shifting from wages to profits.
If wage-profit shares stabilise, even the usual productivity growth rate of 1.5% should keep inflation under 2.0%, as higher productivity more than offsets rising wage costs.
If the productivity boom that AI proponents are promising were to materialise, inflation would be well under target, even with wages rising at current rates. Clearly, wage inflation is not accelerating.
Meanwhile, Trump may raise tariffs again or start another war, raising prices further. But again, raising Fed interest rates cannot help.
Affordability
The popular consensus is that the Iran war was largely responsible for the Republican Party setback in last week’s US mid-term elections.
The war and its consequences are widely seen as primarily responsible for the current US affordability crisis. Trump has raised inflation, not only by waging war, but also by imposing tariffs on most trading partners and sanctions on some.
As higher inflation has been the pretext for the Fed to raise interest rates, it should lower rates if prices fall. And when the AI bubble bursts, interest rates should decline.
Fuel prices jumped by $1.50 per US gallon after the war started and remain over a dollar higher than before. Diesel prices rose by almost $3 per gallon at their peak and remain over $2.50 above their pre-war level.
Food prices are also expected to rise further in the new year due to fertiliser shortages, as much of the world’s supply has come from the Persian Gulf region.
Ironically, Trump’s war has accelerated the green energy transition worldwide, with electric vehicle and solar panel sales soaring, thereby reducing demand for oil and gas in the longer term.
Ending the April 2025 Liberation Day tariffs did not return prices to earlier levels. Similarly, ending the war will only partially reverse the economic disruption and damage caused.
IPS UN Bureau
© Inter Press Service (20261110061436) — All Rights Reserved. Original source: Inter Press Service














 English (US) ·
 French (CA) ·
 French (FR) ·